This is default featured slide 1 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

This is default featured slide 2 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

This is default featured slide 3 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

This is default featured slide 4 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

This is default featured slide 5 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

Showing posts with label credit cards for good credit. Show all posts

Friday, September 23, 2016

The Effect of using Credit Cards for Good Credit

Summary: Eventually when you have an improved credit score, you could decide to change your card to one with a higher limit and that does not require any form of deposit. If you have plans of doing this, it is advisable that you call your credit card Company to request for an upgrade. Your credit history will be reviewed and if it is good enough, they you will get the requested upgrade.

Most lenders chose their specific requirements and in most cases, having a good or bad credit score is just one of the criteria. Having a good or bad credit score a very important factor but each lender has to choose the exact way to select the credit applicant. This is because lenders could decide to check your good or bad credit score from several sources or will look through several credits scoring model, the most import think is the range which you fall in. The main criteria that determine a good or bad credit score is the range which you fall into. These work as a quick reference for a lender. So the main focus of a good or bad credit score is the range which you fall into rather than being overly concerned about the particular score.

It’s very important to understand the different scoring model and their range and how they are being used by potential lenders. It’s necessary to monitor where you stand which is your good or bad credit score. It’s advised that you should use the same scoring model to it won’t turn out to you trying to check the same score using different scale. So select a scoring model and stick with it throughout the whole process. Any improvement you make on one of the models will reflect on others. Always remember that the score can vary every time you check it. As long as the score is kept within a very good range, those slight changes don’t make much difference in your financial health.


When you borrow a given amount of money, having a good or bad credit score does not specifically determine if you will get approved for the loan or if you will be given the best interest rate. Credit agencies review your given credit history to determine if you could make payment of the borrowed money on time. You can have a large amount of debt and still have a very good credit score once you make timely payments for your bills every month. From your credit report, it will be determined if you can afford to make payments for the loan you are applying for. This is why your income and other money that was previously borrowed have a huge impact in rending decisions. Lender will also review the money you owe and the amount you earn and the assets you have available. If you have a good or bad credit score, using one of the best credit cards for good credit can be a very good way to improve your credit score. These credit cards for good credit works just the same way a regular card works. You are get charged for purchases to your account, make monthly payments and also pay a given interest rate on balances that was carried from one month to the next. Some of these credit cards for good credit come with an added advantage where you can make deposit first. His deposits will guard you from card issuers when you don’t make payments and make it easy for someone with good or bad credit score to get approved.

When selecting credit cards for good credit, make sure you go for one that reports to all three credit bureaus. Some cards don’t do this. If your card issuer does not send the reports to these bureaus, your good or bad credit score will not improve no matter how careful you are with your payments. Even if you get a card that requires you to make some down payments, you won’t automatically get credit cards for good credit. You will need to go through an application process and most times, the issuer will have to review your credit score. Each credit check being made by these issuers will result in a slight reduction in the score so it is advisable not to apply for so many cards. If you have been rejected a number of times, check for other options like a card that doesn’t require credit check at all. To improve a good or bad credit score, always try to make payments using credit cards for good credit on time and use a only a small percentage of the given credit to you. 

Thursday, September 8, 2016

How a Cellphone Can Influence Your Good Credit Score

Summary: In all, always make sure you pay your bills on time or else you may find yourself without a working cell phone and a lower score. Regardless of how you decide to pay your cell phone bill, remember to pay your bill on time and in full to avoid fees, charges, and damage to your score.

After paying for a roof over your head, keeping the lights constantly on, a cellphone bill and a device that comes with it is most likely going to be the next thing on the list of top necessary monthly expense.

Here not all bills are the same especially when it can influence your good credit score. Unlike some monthly expenses, like your mortgage or a car payment, paying your cell phone bill can affect your credit in a different way. In the first place you most likely need a good credit score to get a cellphone but the manner in which your cell phone bill is paid for could either hurt your score or not affect it in any way.

Missing a Cellphone Payment

Like every other bill, if you miss a payment or you are not fast about settling your bill, this will greatly affect your good credit score. Some cellphone companies might decide to switch off your service when there is a delay in your payment. But considering the fact that you don’t have a working cellphone, you still carry an outstanding cellphone bill which is unpaid for. Beyond just shutting off your service, you cellphone company will go ahead and report your missing payments to the bureaus and will send your debt to the collection agency which will greatly harm your good credit score range. Any account that has gone as far as that could be pending on your report for as long as seven years.

Paying a Cell phone Bill on Time

It’s normal to assume that paying your cellphone bill on time will boost your good credit score if missing your cellphone bill will reduce your good credit score. But the truth is if you are just paying your cellphone bills directly each month with cash, check or directly deducting it from your account automatically, it won’t have any impact on your good credit score. As long as the cellphone company has not extending any line of credit, your timely payment will not be report to the bureau.

Paying a Cell phone Bill on Time Using a secured Card

In a situation where by you don’t want to link your cellphone bill to your credit card or you do not have enough credit to get a credit card, here is an alternative way that will help you improve your good credit score. It is known the secured card. Just like a debit card, the amount of money you can charge to your secured card is limited to the exact amount which you out down on your card. . If you don’t qualify for a traditional credit card, it’s significantly easier to qualify for a secured card at a bank or union. And the issuer will report your secured card to the card bureaus, which means you are building history by paying your cell phone bill.

Monday, August 29, 2016

Reasons to Check Your Good Credit Report

Summary: When creditors report to the bureaus, there is always a chance that they might make a mistake in the data they send which will later be reflected in your report. By being mindful of this when reviewing your report, you can make sure that these errors are corrected before it's too late.

A lot of people ask why they should always review their good credit report. It is widely believed that this is only for who want to get mortgage a loan or some kind of credit. But the truth apart from the fact that your good credit report is a source of information to determine your creditworthiness; it is also needed for you to review and to ensure that no mistake was made in the report that could mislead lenders or other people requesting your report. This will also have a big impact in your good credit score. Considering the fact that this result is uploaded by people, a lot of mistakes could be made. Certain information could be omitted or there could be a conflict in the information provided which will make it not 100% accurate. Here are some reasons why you should review your good credit report:


Prevention of Identity Theft

When you review your good credit report regularly, you could always ensure that no other account which is not yours have been included in your name and there is no unauthorized transaction attached to your active account. Any new account that is opened using your name without your approval is the first sign of identity theft. This could lead to a disastrous result because you will be held responsible for any accumulated debt in that name. You could also monitor your sending to be sure you are not pilling up debt in any of your accounts.

To Detect Credit Bureau Error

The information available in bureaus is gotten from your records by people and not machines. Considering the fact that those who do this are people and not machines, errors are bound to be found either in a number, a letter, or something of the sort, for example, maybe the person who transcribed your report wrote 1,000 instead of 10,000, which in reality would make a huge difference to what is being reported.

To ensure your Data is Complete in all Three Bureaus

This is very important considering the fact that the three main bureaus in the US which are Equifax, Experian and TransUnion don’t share information. So if you notice when reviewing your good credit report that one or even two of the bureaus are missing some information that was stated in the report from another bureau, report it immediately in order for your good credit report to be updated and to include that data. Sometimes it may also be the case that some negative information is added to only one or two of your good credit reports and which you might not notice if you only check your report from one of the three bureaus.


Wednesday, August 24, 2016

The Impact of Having Good Credit Score

Summary: Managing good credit efficiently leads to a good credit score; this will reduce your cost of borrowing. Great financial moves involve living within your means, paying debt wisely including good credit card minimum payments on time and every time. This will help reduce the amount you pay on interest and keep you with some more money to save and invest.

A lot of people do not know about the credit scoring system or even the score until they are about to purchase a home or get a loan to start a business or make any other major purchase. A Credit score is a three digit number which is used by lenders to make a decision on whether you are going to get a credit card, a mortgage or some other kind of loan. This three digit number also has a huge impact in deciding the interest rate you are charged at when you get the loan. The score is a summary of your chances of being risky to the lender during the course of the application. Every individual have their own unique good credit score, even married couples have their separate good credit scores. When couples sign up as co-signers for a loan, both good credit scores will be scrutinized. The riskier this score is to the lender, the loss likely the lender will release the requested loan and the more interest rate you will get to pay on that loan which implies that you will pay more when you borrow money. Credit Scores ranges from 300 to 850. When it comes down to calculating your interest rate, the higher the score, the better terms you will receive on a loan.


The most used good credit scoring system known was developed by Fair Isaac Corporation which is referred to as FICO score. There are three major bureaus which are Equifax, Experian and TransUnion. These three bureaus make use of FICO scoring model. The score from these three bureaus might not be the same exact score. This is due to the fact that lenders and other businesses report information to the agencies in different manner and these agencies process their information through their system differently. Due to the fact that lenders have different criteria of making a loan, getting the loan depends on the bureau the lender goes to for this score. Suppose you want to borrow $200,000 in the form of a fixed rate thirty-year mortgage. If your good credit score is in the highest category, 760-850, a lender might charge you 3.307 percent interest for the loan. This means a monthly payment of $877. If, however, your score is in a lower range, 620-639 for example, lenders might charge you 4.869 percent that would result in a $1,061 monthly payment. Although quite respectable, the lower score would cost you $184 a month more for your mortgage. Over the life of the loan, you would be paying $66,343 more than if you had the good credit score. Try to imagine what you could do with an extra $184 per month.


Friday, August 12, 2016

Reasons to Understand What Good Credit Score Range Is

Every known lender have their own standard for rating credit scores but any score that is 700 and higher on a scale of 300 to 850 is regarded as a good credit score. Most lenders use this three digit score to know your creditworthiness and your chances of getting the loan from them. The higher this good credit score is, the better your chances of getting the loan from the lender. A good credit score can also help you save on interest rates. Having a particular good credit score is not enough reason for you to get a loan or doesn’t not guarantee getting it at the lowest interest rate available, but a general understanding if where you stand with your score will help you determine the type of offer to apply for and also the areas that should be worked on before the application.

Free report can be gotten from Equifax and TransUnion. It is usually updated every week which makes it easy to track your score. Once this score is known, the next step will be to check your credit factors to get to know what is impacting them which is a very good way in helping you figure out how to improve this score. Another thing to note is the fact that several authorities refer to any score below 500 and 600 is not a good credit score which is seen as the absolute lowest score. When the score gets this low, the only lender that will give loan are those specialized in giving loan to this group of people? Down payment and collateral might not have so much impact when it has gotten to this stage. It will also be very difficult to get insurance and some employers who check good credit reports won’t give you a chance. Such score leaves an individual with very few options and it is advisable not to chance after any until it’s improved. With a low score, it is advisable to focus on reducing debt, eliminate collection accounts and make timely payments.

In most cases, there is usually a bankruptcy, active judgment, or repossession hurting you score or having several active collections. The only other possibility is that you have little to no information on report with which to build a score. Those whose account report information get stuck with low scores. For those who are newbies, it will be easier to build a good credit score than those who have accumulated negative remarks.


Summary: Almost every lender chooses their own criteria and in most cases, this score is just a factor out of others even though it is a major factor. This is due to the fact that lenders pull your scores from several sources or may decide to check through several different scoring models to know the range you fall into. Here the creditors get to decide how exactly he wants to evaluate the applicants. But with a score below 600, it would be perfect to contact a counselor and create an actionable plan to revive your good credit score.

Wednesday, August 10, 2016

Choosing the Best Credit Card for Good Credit

No credit card is unique and fits everyone or every purpose. But by understanding your reason for getting the card and asking question geared towards uncovering the pros and cons of the card, you will know if it will fit your spending habits and credit level. Here are few ways to help you understand the Best Credit Cards for Good Credit for your need:

Know Your Credit

Get to know the credit card that will best fit you based on your credit score. If you have an excellent score, it will give you a very good chance of getting the best credit card for good credit with great perks. A lot of credit card issuers give free access to FICO credit score to their cardholders and so many third party website provide different credit scores.


Get to know the best credit card for good credit you need

There is generally some best credit card for good credit:

-Cards which will help you improve your credit score when it is low

-Cards that will save you money on interest

-Cards that will get you rewards

The Best Credit Card for Good Credit that will suit you is the one that has features that will fit your specific needs. For example if you travel a lot, you will most likely want to go for the best travel card in the world.

If you want to build or improve Credit

Student card and secured card are specially made for college students who are new to credit and are easier to get than other best credit cards for good credit available. A secured card generally requires a minimum deposit of about $200.This deposit will then be refunded when the account is upgraded or closed while maintaining a good score.

If you want to save on Interest

You will likely prefer a card with 0% APR and continuous low interest rate. This card will be very useful if you want to use the best credit card for good credit for emergencies and also as an irregular income and carry a balance regularly. Balance transfer is a good way to help you pay high-interest debt interest-free. You should also understand that these deals are rarely gotten by people with fair and poor credit score.

If you want to earn rewards or cash back

A reward card is perfect for someone that always pays off the balance every month in full and doesn’t pile up interest. These cards usually comes with a higher APR but also offer great sign-up bonuses and gives you points, miles or cash back on every amount that is being spent.


Related Resource: How to Build Good Credit

Summary: Finding the Best Credit Card for Good Credit is part art, part science. If your number falls below your expectations, you can check the credit report to know the reason why. You can then focus on how to improve that score, from working on your spending habits to following up on error on your credit reports, if necessary. You are entitled to one free copy of your credit report from each of the three major credit bureaus every year.

Wednesday, June 29, 2016

What Is a Good Credit Score Range?

Summary: With your score still being within the good credit score range, you will be accepted for every kind of credit and the least interest rate as long as it doesn’t go below this point. You will qualify for almost every loan and this good credit score range won’t hold you from getting insurance and finding employment.

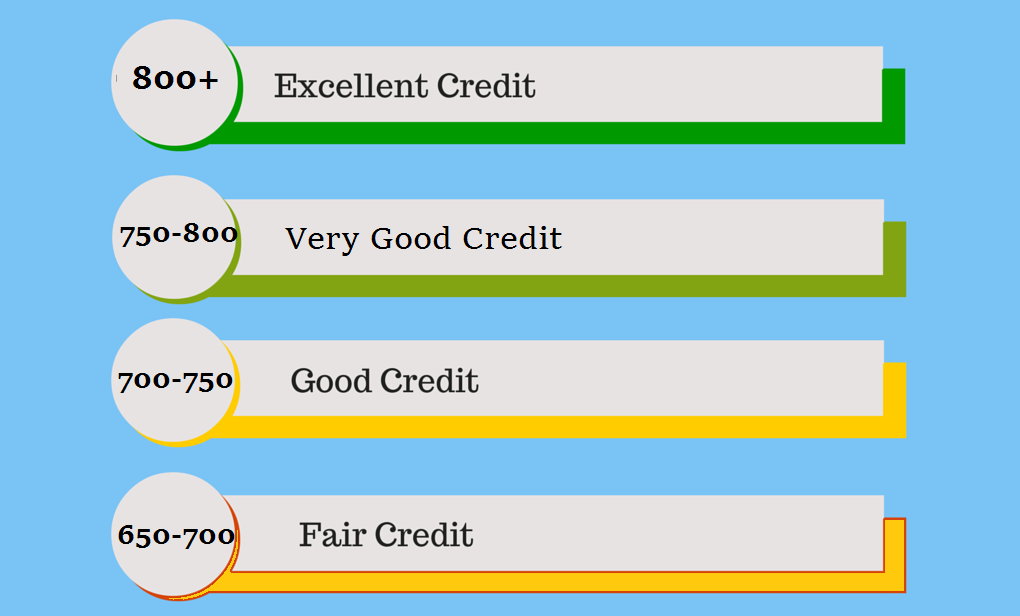
Generally speaking when your credit score is above 700, it can answers the question of what is a good credit score range. However, if you surf the internet you will see a lot of comments of what a good credit score range is. This makes sense because it reflects the industry considering the fact that every lender has their own criteria when determining the credit worthiness of an individual. Analyzing credit scores into ranges is the easiest way to understand when you are within the good credit score range. It gives you the clear picture of where are and also answers the question of ‘what is a good credit score’. It will also let your understand how you would be treated by potential lenders, insurance companies, and even potential employers. With this you will have a clear understanding of what good credit score ranges is and how it makes you seem in the eyes of lenders.


To most lenders, there is only very little difference between 750 and 800. With this good credit score range, you will get approved and offered the best interest rates just the same way they treat customers with excellent credit score. The only difference between the treatments people in this rage get over the people in excellent credit score range is their debt to income ration. This will only be short of excellence due to few late payments and also delay in payments in work place. With a score between 700 and 749, you will still get approval as you still fall within the range of a good credit score. You might not be given the lowest interest rates and VIP treatment like others above this good credit score range. With this you obviously have a great credit history but must have had a collection account somewhere along the line. Probably a late payment a while ago or might just have had too much credit debt. But irrespective of all that, you are still in good shape.

Related Source: https://goodcreditblog.wordpress.com/2016/06/15/understanding-good-credit-scores/